How to Choose a Cofounder: Test the Partnership Before You Split the Shares
The person you start a company with will own part of it long after the excitement wears off. The choice is usually made over coffee, between two people who like each other, and the shares are split before either has done a week of real work alongside the other. For a while nothing tests it. Then the company has a bad quarter, raises money or gets an offer, and the choice is judged by people who were not in the room. Knowing how to choose a cofounder mostly means running that test yourself, early, while failing it is still cheap.
Do You Need a Cofounder at All?
You need a cofounder when the company depends on a skill or a level of commitment you cannot hire yet, and you need it from the first month. If the gap is a task you can pay someone to do, hire for it. A cofounder owns part of the company for good.
The case for having one is real, especially if you plan to raise money. Carta's 2025 Founder Ownership Report found that solo founders led 35 percent of the startups incorporated on its platform in 2024, but only 17 percent of the startups founded that year that had closed a venture round by the end of it. Paul Graham put the investor's view bluntly in 2006: a single founder is "a vote of no confidence", because it suggests nobody who knew the founder well would join them.
The case against is just as real. A cofounder is the most expensive way to fill a gap. An early hire who does not work out can be let go; a cofounder who does not work out keeps whatever has vested and a voice in the company. If what you want is someone to share the worry rather than the work, that is a job for a mentor or an experienced independent director, and neither needs a share of the company.
What to Look for in a Cofounder
Look for the skill you lack, the same ambition, and proof of how they behave when things go wrong. Liking each other matters, but it is the least useful thing to test, because almost every pair of cofounders starts out liking each other.
Start with the gap. Most founders are builders, and many go looking for another builder: a second engineer, a second product mind. Two builders still have nobody selling. Someone has to own the customer from the first week, because the first sales are made by founders, not hires, and those sales teach the company who buys and why.
| What to check | How to test it | Stop if |
|---|---|---|
| The skill you lack | Give them the hardest part of that job during the trial | They hand it back or want to hire someone for it |
| The same ambition | Ask what they would sell the company for, and when | One of you wants a sale in seven years, the other a business for life |
| Money and months | Ask how many months they can go unpaid | The answer depends on raising money soon |
| A bad week | Watch what they do when a deal falls through or a deadline slips | They blame someone, go quiet or retell what happened |
| How they disagree | Disagree on something real and see how it gets settled | Every disagreement ends with the same person giving in |
| Who vouches for them | Speak to a former partner and someone who reported to them | Nobody from their past work will talk, or the stories do not match |
Every guide on how to choose a cofounder tells you to look for shared values. The rows above are how values show up in practice, and each one can be checked rather than assumed.
How to Test a Cofounder Before You Commit
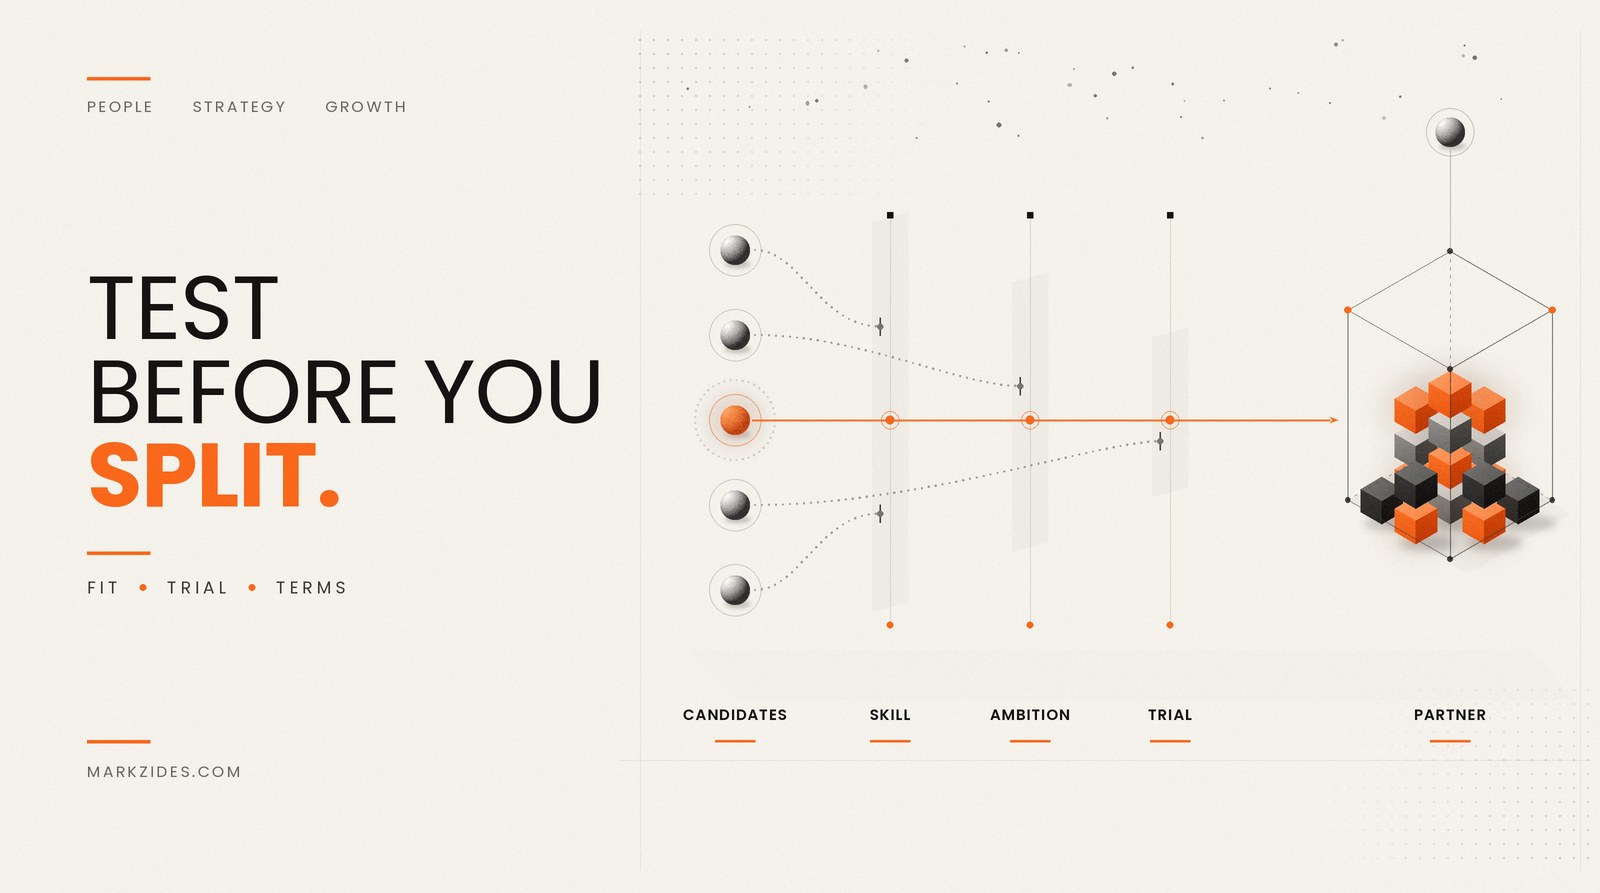
Test a cofounder the way you would test anything expensive: in conditions close to the real thing, for long enough to see a bad week, with a date to decide. Four steps do it.
- Have the hard conversations first. Before any work starts, settle money, roles, ambition and what happens if one of you leaves. A candidate who will not have these conversations now will not have them later, when they are harder.
- Work together on something real for six to twelve weeks. Not a business plan or a weekend project: a problem with a customer at the end of it. The best trial is winning a first paying customer together, because it tests the product, the selling and the partnership at once. If you both keep your jobs for now, agree the hours each week and check them.
- Speak to people they did not choose. A former cofounder, someone who reported to them, a customer they let down. Ask what they were like when things went wrong. The references a candidate offers will praise them; the useful ones are the people they did not offer.
- Decide on a set date and write it down. At the end of the trial, say yes or no. "Let's keep going and see" is a no that costs another three months. If the answer is yes, the terms go into a written agreement before any shares are issued.
None of this is a formality. In the same 2006 essay, Graham wrote that about 20 percent of the startups his firm had funded had seen a founder leave, often enough that it began advising founders to vest their shares. A trial will not prevent every departure, but it moves the likeliest ones to before the shares are split.
Questions to Ask a Potential Cofounder
Ask these before the trial starts and again at the end. What matters is whether the answers match yours, and whether the candidate is willing to answer at all.
- Money. How many months can you work without pay? Will you put money in, and how much? What happens if we need to raise and cannot?
- Time. When can you go full time? What else is competing for your week?
- Roles. Who decides on the product? Who sells? Who is chief executive, and what happens if investors later want someone else?
- Ambition. Do you want to sell the company one day, and at what number would you say yes? How big does this have to get to be worth it to you?
- Conflict. Tell me about a partnership or a job that ended badly. What was your part in it? How should we settle a disagreement neither of us will give up?
- Leaving. If you leave in the first year, what should happen to your shares? What if I leave?
Write the answers down. Together they are the first draft of your founder agreement, and the places where your answers differ are the terms you will need to negotiate.
Cofounder Red Flags
Most red flags show up in the first few weeks, if you are looking for them. Each one is a reason to end the trial, not to negotiate around it.
- They want the title before the work. Being named chief executive or chief technology officer matters to them before anything is built.
- They will not put anything at risk. No time away from their job, no money in, but a full founder's share.
- They avoid the shares conversation. "We'll sort that out later" usually means one of you will be unhappy later.
- Nobody from their past will vouch for them. Or every venture they left ended because of someone else.
- They need the credit. The wins are theirs and the problems belong to someone else.
- Roles stay vague. After weeks of working together, you still cannot say who decides what.
Agree the Split and the Terms Before You Start
Split the shares on what each person will bring, make them vest, and write down the terms while you still agree on everything.
There is no correct cofounder equity split, and an equal one is common. Carta found that 45.9 percent of two-founder teams that incorporated in 2024 split their shares equally, and that the median split for two founders was 55 to 45. The risk is not an equal split but a fast one. Thomas Hellmann and Noam Wasserman studied 1,476 founders in 511 startups and found that equal splits were associated with lower valuations in the first funding round, an effect that was stronger in teams that settled the split quickly. Their explanation is that a quick even split tends to paper over real differences between the founders.
Then make the shares vest. A common arrangement is four years, with nothing vesting until the end of the first, so a founder who leaves early keeps only what they earned. This is why splitting the shares on day one with nothing written down does so much damage: a founder who walks away in the first year keeps a full share of a company they no longer build.
| Term | What it settles |
|---|---|
| Roles | Who does which job, and who has the final say in each area |
| Decision rights | Which decisions need both founders, and how a deadlock is broken |
| Vesting | How shares are earned over time, and what happens to unvested shares when someone leaves |
| Ownership of work | That the product, code, brand and customer contracts belong to the company, not to a founder |
| Leaving | Notice, handing over work, and whether a departing founder can compete |
| Commitment | Hours, pay, and any money each founder puts in |
Have a lawyer draw it up. An agreement written while you both agree is quick to settle; the same agreement negotiated after one of you has stopped speaking to the other is slow, costly and sometimes impossible.
How Your Cofounder Choice Shows Up When You Sell
Years later, a buyer reads the result of this decision in three places: the share register, the organization chart and the contracts.
- The share register. A cofounder who left in year two and kept a large stake is someone the buyer has to negotiate with, though they have done no work for years.
- The organization chart. If the business depends on both founders, the buyer is paying for two people who may not want to stay. A company that keeps running when its founders step back is worth more for exactly that reason.
- The contracts. Product or code a founder wrote before the company existed, and never signed over to it, is a gap that shows up in the checks a buyer runs before making an offer.
Each of these is fixed in the first year by the terms in the previous section. Each costs far more to fix during a sale, when the founder who left knows the deal needs their signature.
Frequently Asked Questions
Should your cofounder be a friend?
A friend can be a good cofounder, but friendship is not the test. Friends often skip the hard conversations to protect the friendship, and that is how shares get split badly. Ask a friend the same questions and run the same trial you would with a stranger, then decide whether the company is worth risking the friendship.
How long should you know someone before starting a company with them?
Long enough to have worked together through at least one bad week. There is no set number of years. Ten years of friendship tells you less than three months of real work on a shared problem, because the work shows how they act under pressure and how they disagree with you.
What is a fair equity split between cofounders?
One that reflects what each founder will bring: the idea, the skills, any money, and the time they commit from here on. An equal split is fine when those really are equal. Agreed quickly, it often hides differences. Whatever the split, make the shares vest and put it in writing.
Do you need a technical cofounder?
If the product is the hard part, yes: someone with a stake in the company has to own it. If the product can be built by people you hire, a technical cofounder is optional, and the scarcer skill may be selling what gets built.
What happens if a cofounder wants to leave?
It depends on what you agreed. With vesting, a departing founder keeps the shares they have earned and the unvested rest goes back to the company. Without it, they may keep their full share. A written agreement should also cover notice, handing over work, and whether they can compete.
Final Thought
Choosing a cofounder is the first decision about how the company will be run, and it is made before there is a company to run. That is the O in Mark's UNLOCK Method, organize for growth: decide who owns what at the top before the pressure arrives, test it while walking away is still cheap, and write it down. A company organized that way is easier to fund, easier to grow and easier to sell, which is why planning an exit starts with the people who own it.
Ready to build a revenue engine that runs without you?
Mark works alongside founders as a player-coach — not a slide deck.
Book a 30-minute call