How to Build an Advisory Board That Is Worth Everyone's Time
You already have a few people you ring when you are stuck. A former boss who has run something bigger. The accountant who has seen countless companies like yours. A friend who sold a business and knows what buyers look for. The calls help, but they are scattered. Each person sees one corner of the company, hears the story your way, and answers before knowing the rest. Nobody sees the whole picture, and nobody asks later what happened. The same people, seated as an advisory board with a date and the real numbers, would be worth far more.
What Is an Advisory Board?
An advisory board is a small group of experienced people who meet the owner on a fixed schedule to advise on the company's biggest decisions. Its members have no vote, no legal duties to the company and no power to make anyone do anything. The owner listens, then decides.
That is the whole difference from a board of directors. A director who votes and carries legal duties can overrule the chief executive and answers to the shareholders. An advisor answers to the owner and can be ignored. Many owners want exactly that: experienced views without handing over control, and without the board seat and veto that come with investors' money.
Do You Need an Advisory Board?
Few owners have one. When BDC, Canada's business development bank, studied advisory boards in 2014, only 6 percent of Canadian small and medium-sized businesses used one. Of those without one, 57 percent said setting it up looked like too much work, time and effort.
The firms that had one did better. Their sales grew 67 percent on average in the three years after they set up a board, against 23 percent in the three years before, and productivity rose 6 percent against 3 percent. From 2001 to 2011, their average annual sales were 24 percent higher than a comparison group's. That is an association, not proof: owners who set up a board may already have been about to grow. But it is the clearest evidence available, and it points one way.
You probably need one if:
- decisions you have never made before are coming: your first senior hire, a new market, raising money, a sale
- you are the only senior person, as many founders who run the company alone are
- nobody in the company pushes back on you any more
How to Build an Advisory Board in 7 Steps
The steps build the board around decisions rather than names. That is what keeps it useful after the first few meetings, when boards built on names tend to drift into polite updates.
1. List the Decisions of the Next Eighteen Months
Write down the big decisions the company will face in the next year and a half. Not goals, decisions: whether to hire a sales leader, whether to enter a second market, whether to raise money or borrow, when to start preparing for a sale, how to price a new service. Aim for four to six.
Those decisions are the board's job description. If you cannot list any, you do not need a board yet. You may need a mentor.
Do this: Write the list on one page, with the date by which each decision has to be made.
2. Turn Each Decision Into a Seat
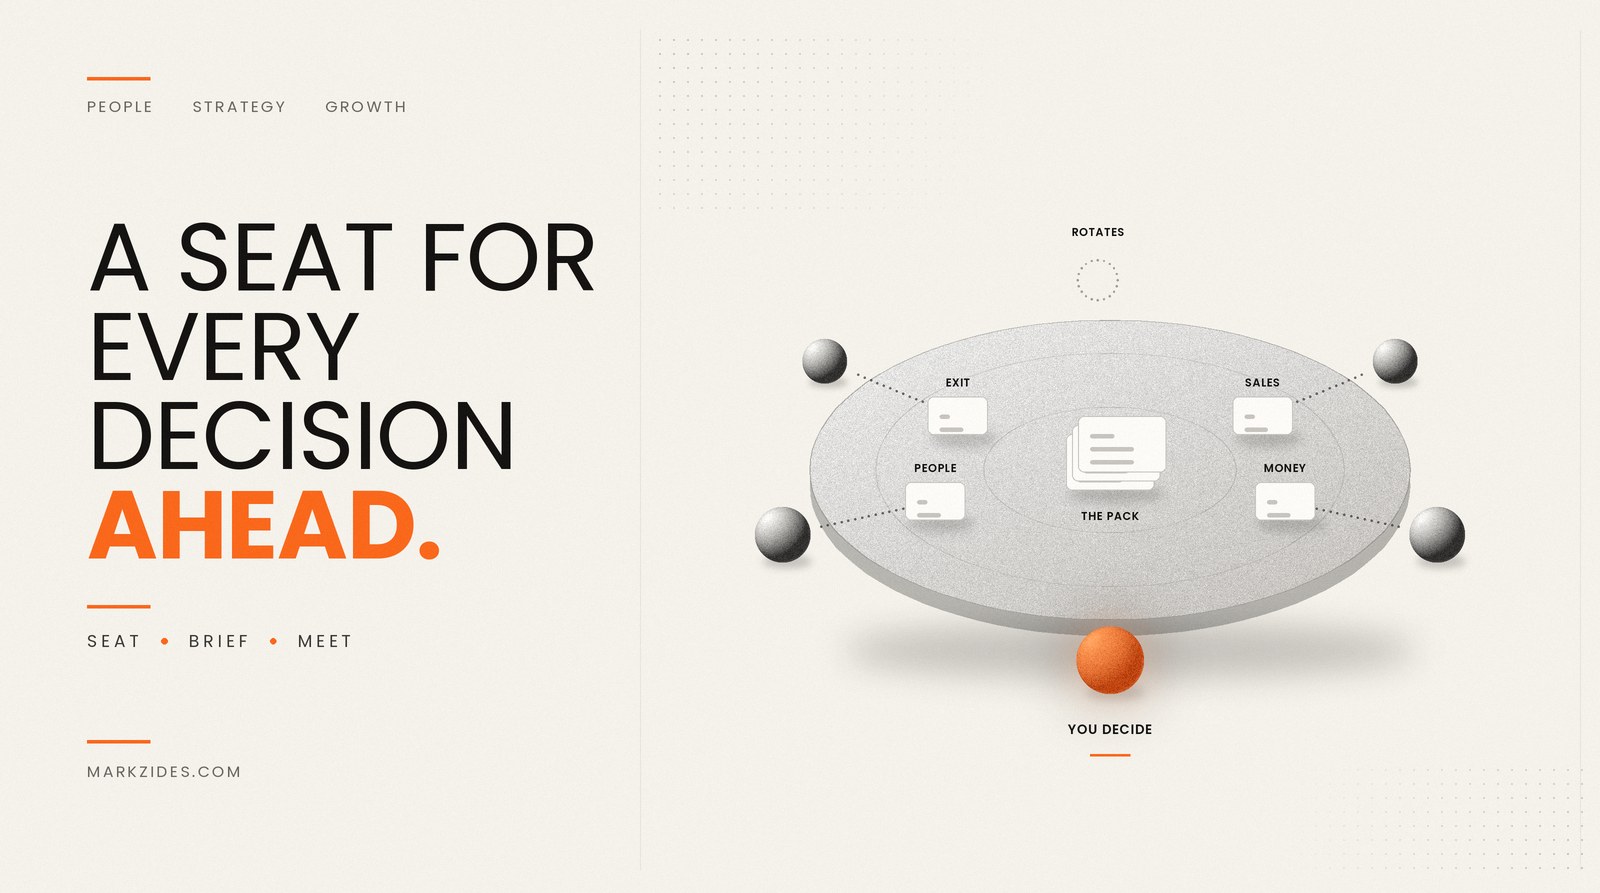
Each decision needs someone who has made it before, at a company about your size. That person fills a seat. Some advisors can cover two seats; few can cover more. Keep the board small: three to five seats is easier to fill, easier to run and harder to hide in.
| Decision ahead | The seat | Who fits it |
|---|---|---|
| Preparing to sell in the next few years | Exit | Someone who has sold a company your size, ideally to the kind of buyer you expect |
| Hiring the first sales leader | Revenue | A former sales leader who built a team at your stage |
| Entering a new market | Market | Someone who has sold into that market, not someone who advises on it |
| Raising money or taking on debt | Finance | A former finance leader, or a founder who has raised or borrowed at your size |
| Building a leadership team | People | Someone who has grown a team through the size you are heading for |
| Launching or repricing a service | Customer | A senior buyer from the kind of company you sell to |
The exit seat is the one owners tend to add too late. Planning a sale years before it happens is where an advisor who has been through one earns their place.
Do this: Next to each decision on your list, write the seat and the kind of person who fits it.
3. Write a One-Page Brief for Each Seat
A brief turns a vague favour into a clear role. It also makes the ask easier, because the person can see exactly what you want, and what you do not. Copy this outline:
- The decision. What you have to decide, and by when.
- The experience it needs. What the person has done that makes their view worth having.
- The time asked. Meetings a year, how long each one runs, and any calls between them.
- What they get. The reward, in plain terms.
- The term. One year, renewable.
- What you will send. The pack a week before each meeting.
Do this: Write the briefs for your first two seats before you approach anyone.
4. Find and Ask the Right People
Look for people who have made the decision, not people who sell services into it. Your accountant, lawyer and banker are worth keeping close, but you pay them, and they may hesitate to tell you the hard thing. Keep them as advisers to the company, not members of the board. The same goes for friends: kind is not the same as useful.
The best candidates are often one introduction away: former founders, retired executives, senior people at companies a stage or two ahead of yours. Ask for one working session on a real decision before anyone commits. You will both learn more from that than from any conversation about the role.
Do this: List three names for each seat, and ask the first for a single working session.
5. Agree It in Writing
A short agreement saves awkward conversations later. Have a lawyer draft it, and check it covers these points:
| What to cover | Why it matters |
|---|---|
| The role, and that it carries no authority | The advisor cannot act for the company or commit it to anything, and is not a director |
| Time | How many meetings a year, and how much contact between them |
| Reward | What they receive, and when |
| Confidentiality | They will see your numbers and your plans |
| Conflicts | They tell you if they advise or invest in a competitor, customer or supplier |
| Ideas and work they contribute | Who owns anything they create for the company |
| Term and ending | One year, renewable, and how either side can end it early without fuss |
Do this: Send the agreement with the brief, so the person says yes to the role and the terms together.
6. Run Meetings on a Fixed Rhythm
Meet every quarter for two to three hours, on dates fixed a year ahead, and fit the meetings into the fixed rhythm of reviews the company already runs on, so they land when the numbers are fresh. Send a short pack a week before: the numbers since last time, what you decided last time and what happened, and the one or two decisions you want help with. Advisors who have read the pack arrive ready to think. Advisors who hear it for the first time in the room spend the meeting catching up.
Then spend the meeting on decisions, not updates. This agenda is a starting point:
Write down what you decided, and why, before everyone leaves. The next meeting starts by checking it.
Do this: Fix the four meeting dates for the year before the first meeting, and send the first pack a week ahead.
7. Review, Reward and Rotate
Once a year, review the board the way you would review any team. Did each advisor come prepared? Did their advice change a decision? Is their seat still the right one, now that some decisions are made and new ones are coming?
When a decision has been made, its seat may no longer be needed. Thank the advisor, end the term as the agreement says, and fill the next seat. A one-year term that renews makes this a normal event rather than a sacking.
Do this: Put the annual review in the diary for the anniversary of the first meeting.
How to Reward Advisory Board Members
There is no standard reward. Owners usually choose one of four, or a mix:
- A fee for time. Simple, and right when you ask for real hours between meetings.
- A small stake that vests over the term. Often used by companies planning to raise money or sell. It ties the advisor to the outcome, but shares are permanent, so they should vest over time and stop vesting when the term ends.
- Expenses only. Travel and meals for meetings, and nothing else.
- The work itself. Many experienced people enjoy staying close to a growing company, and some will say yes for the challenge and the people they meet.
Match the reward to the time you ask for. A quarterly meeting is a small ask; a monthly call plus introductions is a large one. Take tax and legal advice before offering anyone shares.
Common Advisory Board Mistakes
- Choosing names, not decisions. An impressive board with nothing to decide drifts. Fill seats from the decision list.
- Running meetings as updates. Send the numbers ahead and spend the time on decisions.
- Filling seats with friends and paid suppliers. Ask people with no reason to flatter you.
- No term. Without one, the only way to change the board is an awkward conversation. One year, renewable, written down.
- Treating advice as orders, or ignoring it every time. Listen, decide, and tell the board what you decided and why. Advisors who never see their advice used soon stop giving it.
Frequently Asked Questions
How many people should be on an advisory board?
Fewer than most owners think. Three to five people, each in a seat tied to a decision the company faces, is enough for most small companies and easy to run. Add a seat when a new decision needs one, and let a seat go once its decision has been made.
Do advisory board members get paid?
Sometimes. Owners pay a fee for time, offer a small stake that vests over the term, cover expenses only, or rely on the advisor's interest in the work. Match the reward to the time you ask for, write it into the agreement, and take tax and legal advice before offering shares.
What is the difference between an advisory board and a board of directors?
A board of directors has legal duties, votes on decisions and can overrule the chief executive. An advisory board has no vote, no legal duties and no power; it advises the owner, who decides. Many owners start with an advisory board and add an independent director as the company grows.
How often should an advisory board meet?
Quarterly suits most small companies: often enough to follow the big decisions, rarely enough that advisors can prepare properly. Fix the dates a year ahead, send a short pack a week before each meeting, and allow calls between meetings when a decision cannot wait.
How do you ask someone to join your advisory board?
Send a short note naming the decision you want help with and why their experience fits it, with the one-page brief for the seat. Ask for one working session on a real decision before any commitment. People say yes more readily to a clear, specific role than to a vague favour.
Final Thought
An advisory board is only as useful as the questions you bring it. Build it around the decisions ahead, give each one a seat, send the numbers early and spend the time deciding, and the people you already ring when you are stuck become one of the most useful parts of the company. That is the N in Mark's UNLOCK Method: name the growth levers, so the decisions that move the company get the best thinking available. Mark is a six-time founder with three exits, and helping owners work out which decisions their board should be working on is part of the work of a growth advisor.
Ready to build a revenue engine that runs without you?
Mark works alongside founders as a player-coach — not a slide deck.
Book a 30-minute call