Selling Your Business to Private Equity: What Firms Pay, What They Expect, and What You Keep
The letter from a private equity firm reads like the finish line. Someone wants to buy the company you built, at a number that changes your life. For most founders, though, selling your business to private equity is not an ending. It is the start of a plan with a deadline, run by people whose job is to sell the company again, often with part of your own money still inside it. The founders who do well go in knowing what the firm is really buying, what it will ask of them afterwards, and what they get to keep.
What Does Selling Your Business to Private Equity Mean?
Selling your business to private equity means selling most or all of your company to an investment fund. The fund pays with its investors' money and with money borrowed against your company, works to grow the business, and then sells it on, usually within about five years. You are paid at closing, and often again at that next sale.
The fund's own investors expect a return, and that shapes everything that follows. The firms in Pepperdine University's 2025 Private Capital Markets Report target a median return of 25 percent a year and expect about 20. That return has to come from your company: from growth, from paying down the debt, and from selling it for more than they paid.
Your company is bought in one of two ways. As a platform, it becomes the base the firm builds on, usually with you or a new chief executive running it. As an add-on, it is joined to a company the firm already owns, and you usually report to that company's leaders.
Should You Sell Your Business to Private Equity?
It suits some companies and owners far better than others. The largest group of firms in the Pepperdine survey, 30 percent, most often invest $5 million to $10 million in a deal, and their most common buyout was a company with $1 million to $5 million of EBITDA. Business services and manufacturing take the largest shares of the money they plan to invest, 21 and 19 percent.
| Good fit | Poor fit | |
|---|---|---|
| Size | EBITDA of $1 million or more, with records that prove it | Profit that depends on how the owner's costs are counted |
| Growth | A believable path to 15 to 20 percent growth a year | Flat for years, with no clear next market |
| Team | Managers who run the company day to day | Every decision and key customer runs through the owner |
| Customers | Revenue spread across many accounts, much of it repeat | One or two customers carrying the business |
| What you want | Cash now, plus a stake in a bigger second sale | A clean exit with no ties, or full control after the sale |
If what you want is a clean break, a sale to another company or to your own managers may fit better. Each kind of buyer prices the same company differently, so decide which outcome you want before you decide who to sell to.
How to Sell Your Business to Private Equity in 6 Steps
The firm has run this process many times. Most founders run it once. These six steps close that gap.
1. Decide What You Want From the Sale
Before the first meeting, write down three things: the cash you need at closing, whether you want a second payment later, and whether you want to keep running the company. Then write down your walk-away number. A firm will ask early what you are looking for. An owner who knows the answer negotiates from it. One who does not ends up negotiating from the firm's first offer.
2. Recast Your Earnings Before They Do
Firms price most deals as a multiple of EBITDA, and the firms surveyed gave recast EBITDA, earnings adjusted for one-off and owner-specific costs, more weight than any other multiple (38 percent). Each adjustment you claim is an add-back, and each one needs paper behind it. A salary you pay yourself above the market rate, a one-off legal bill, a relative on the payroll who does no work: list every one, with the invoice or payroll record that proves it. The firm's accountants will test each line, and an add-back you cannot prove comes off the price.
3. Write the Growth Plan They Will Underwrite
A firm pays for the company it thinks yours can become. The firms surveyed expect revenue to grow 20 percent a year after they buy, and EBITDA 23 percent. Show them where that growth comes from, line by line: prices, new customer groups, new products, sales hires and smaller companies worth buying. A growth plan that shows where each point comes from is more believable than a steep line on a chart, and it gives you something to hold the firm to once you are both working to it.
4. Take Yourself Out of the Revenue
The firms rated the management team 4.21 out of 5 for importance when judging a company's risk, second only to its future prospects. If the biggest customers buy because of you and every price is set by you, the firm is buying revenue that might leave with its founder. It will price that in, or hold back part of the price until the revenue has survived the handover. A business that runs without its founder is worth more to every buyer, and to this one most of all.
5. Talk to Several Firms at Once
Firms look at a great many companies to make one investment. For each deal they closed, the firms surveyed reviewed a median of 98 business plans, met the owners of 10 companies, sent 6 term sheets and signed 2 letters of intent.
So one letter of intent is not a sale. Keep at least two firms in the process until the money arrives, and say so plainly: "We are talking to other groups and expect letters by the end of the month."
6. Compare Offers on What You Keep, Not the Headline
Two offers at the same price can leave you with very different amounts. Line them up on the cash at closing, the debt the firm will put on the company, how much you roll over, any earnout, and the role you are offered. Have your accountant model the after-tax result of each before you choose. Then expect due diligence to take over much of your time until closing, as the firm's accountants and lawyers go through the company line by line.
What Private Equity Firms Pay
Less than most owners hope, and in a narrow range. The firms surveyed paid a typical 4 to 5.5 times EBITDA for their buyouts, and the multiple did not climb steadily with size.
| Company EBITDA | Typical multiple paid | Share of equity the firm bought | Years to planned exit | Deals reported |
|---|---|---|---|---|
| Under $1 million | 4.2x | 86% | 7 | 20 |
| $1 million to $5 million | 5.0x | 76% | 5 | 24 |
| $5 million to $10 million | 5.5x | 86% | 5 | 6 |
| $10 million to $25 million | 5.0x | 96% | 3 | 9 |
These are medians from small samples, 6 to 24 deals in each size band, so read them as a guide rather than a price list. Source: Pepperdine Private Capital Markets Report 2025, private equity survey, buyout transactions.
Two things follow. First, the multiple is applied to recast EBITDA, so every add-back you can prove is worth about five times its value: $100,000 of proven costs that will not continue adds about $500,000 to the price. Second, the firms bought between 76 and 96 percent of the equity, so in a typical deal a slice of the company stays with other owners.
A worked line: a company with $3 million of recast EBITDA, at 5.0 times, is valued at $15 million. That is the value of the whole business. Any debt it already carries, the fees, and the terms in the next section all come out before you see the cash.
How the Price Is Paid: Debt, Rollover and Earnouts
A private equity firm rarely pays the whole price in cash from its own fund. Four things decide how much of it you take home.
Debt
The firm borrows a large part of the price, and the loan sits on your company, not on the fund. In the buyouts of companies with $1 million to $5 million of EBITDA, equity made up 56 percent of the money used; the rest was borrowed. Your company's cash repays that loan. It is why firms care so much about steady cash flow, and why the business will feel tighter after the sale.
Rollover Equity and the Second Bite of the Apple
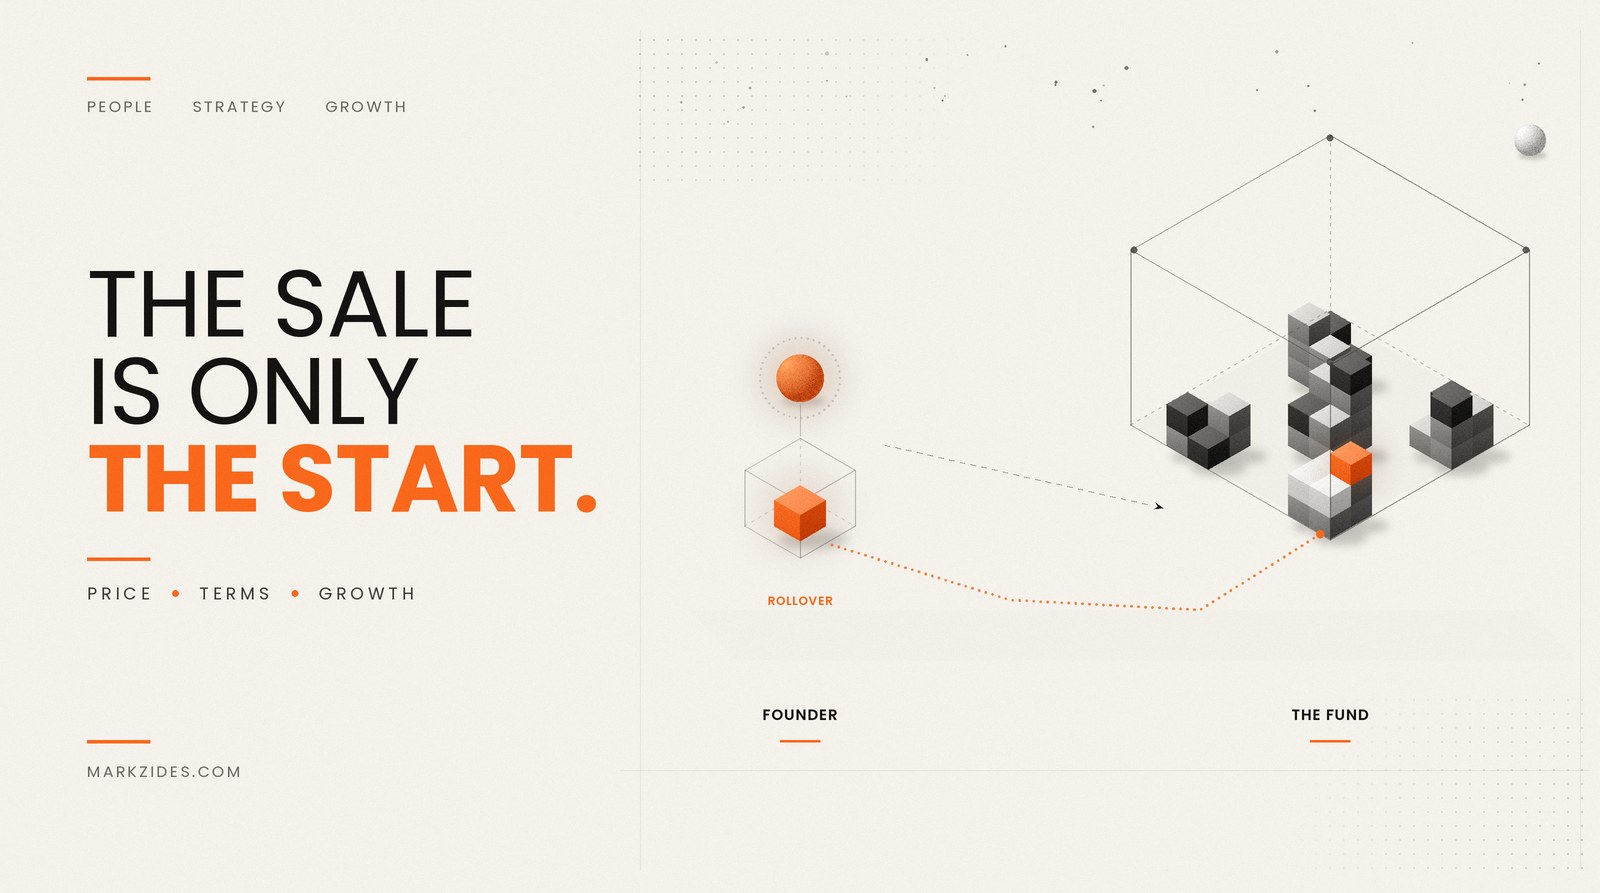
Rollover means reinvesting part of your price in the company alongside the firm. Investment bankers in the same report said rollover equity was used to close half of their deals. It is the source of the second bite of the apple: when the firm sells, your stake is sold with it. It is also a minority stake in a company with debt on it and someone else in control, so roll only what you could afford to lose.
Earnouts
An earnout pays part of the price later if the company hits targets after the sale. Agree to one only on numbers you will still control, measured in a way you can check.
Your Employment Agreement
Most firms want the founder to stay for a while. Agree in writing how long, in what role, with what authority, and what ends it. The non-compete beside it sets how long you cannot start or join a competitor.
Holdbacks and working capital adjustments are terms that move the price after you sign, and each needs a number agreed before the letter of intent.
What Happens After Private Equity Buys Your Company
The firm starts working to its plan on the day the deal closes, and the plan has a growth target. The firms surveyed set a minimum of 13 percent revenue growth a year for the companies they buy and expect 20 percent. For EBITDA, the figures are 15 and 23 percent.
Here is what that means for the second bite, using those numbers. Take a company with $3 million of EBITDA, bought at 5.0 times for $15 million. If EBITDA grows 23 percent a year for five years, it reaches about $8.4 million, and the company is worth about $42 million at the same multiple. At the 15 percent minimum, EBITDA reaches about $6 million and the company is worth about $30 million. This is an illustration, not a forecast. When the company is sold again, the debt is repaid first and the shareholders share what is left, so your rolled stake depends on how much debt remains and on the terms of your shares.
Inside the company, expect five changes:
- A board. The firm takes seats on it, and big decisions such as the budget, senior hires and acquisitions need its approval.
- Monthly reporting. A fixed set of numbers, every month, measured against the plan.
- New senior hires, often in finance first.
- Acquisitions. If yours is the platform, the firm will look for smaller companies to buy and join to it.
- The next sale. 42 percent of the firms' exit plans are a sale to another private equity firm, and 29 percent a sale to a private company. Thirteen of the 20 firms that answered said expected holding periods had grown over the past year, so do not count on the five years in the table above.
For employees, the first months bring new reporting, new systems and often new senior managers. The people who used to get decisions straight from the founder feel it most. Tell your team early what is changing and what is not, and promise only what you control.
The growth target lands on sales first. Price rises, new markets and new products all need a sales team that can sell them without you. If the selling still runs through you, handing off founder-led sales becomes the first item in the plan, whether it is written there or not.
Questions to Ask a Private Equity Firm Before You Sign
The firm will study your company for months. Study the firm back. Ask each one the same questions and compare the answers.
| Question | Why it matters | A good answer sounds like |
|---|---|---|
| How many companies like ours have you bought, and how many have you sold? | Shows whether they finish what they start | Names and dates, including how each one was sold |
| Can I speak to two founders you bought from, including one where it went badly? | References they did not choose | A quick yes, with phone numbers |
| What growth does your model assume, year by year? | It becomes the plan you are measured against | A figure for each year, and where it comes from |
| How much debt will the company carry at closing, and how is it repaid? | The debt is repaid before the shareholders | An amount, a rate and a repayment schedule |
| What happens to my rolled shares if you sell in year three, or in year eight? | Your second payment depends on their timing | Your shares sold on the same terms as theirs, in writing |
| Who sits on the board, and which decisions need its approval? | Sets out what you still control | Names, and a short written list of decisions |
| What is the plan for my management team? | Tells you who stays and who is replaced | Names, roles and any hires planned |
Common Mistakes When Selling to Private Equity
- Talking to one firm. With no competing offer, the first term sheet becomes the ceiling.
- Treating the letter of intent as the deal. The price can still move in due diligence.
- Rolling more than you can afford to lose. Rolled equity is paid after the debt.
- Agreeing to an earnout on numbers you will not control. The firm sets the budget once it owns the company.
- Staying on with no written role. A chief executive title means little if the board decides everything that matters.
- Claiming add-backs with nothing behind them. Each one that fails comes off the price at the full multiple.
Frequently Asked Questions
How long does it take to sell a business to private equity?
Several months once a firm makes an offer, and longer if the books need work first. In the 2025 Pepperdine survey of business brokers, the median time from offer to closing was 2 months for the smallest companies and 4 months for those above $5 million, across every kind of buyer.
What size business does private equity buy?
Mostly the lower middle market. In the 2025 Pepperdine survey, the most common buyout was a company with $1 million to $5 million of EBITDA, and the largest group of firms most often invests $5 million to $10 million. Smaller companies can still sell to private equity, usually as add-ons to a company the firm already owns.
Do I have to stay after selling to private equity?
Usually, for a time. Most firms want the founder to stay through the handover, and some want them to keep running the company. How long, in what role and on what terms is set in your employment agreement, so negotiate it before the letter of intent, while you still have other offers.
What is the second bite of the apple?
It is the second payment a founder can receive when the private equity firm sells the company again. You get it by rolling part of your sale price into the company at the first sale. Its size depends on how much the company grows, how much debt is left, and the terms of your shares.
What happens to employees when private equity buys a company?
The day-to-day work usually goes on, but the way the company is run changes. Expect new reporting, tighter budgets, new systems and often new senior managers. Some roles change or go, especially when the firm joins the company to others it owns. Telling the team early what is changing keeps good people from leaving.
Is selling to private equity better than selling to another company?
It depends on what you want. A company buying a competitor or supplier sometimes pays a premium for the fit and usually wants a clean handover. A private equity firm often pays part of the price later, through rolled equity, and wants you to help it grow the business. Compare the cash you keep, not the headline price.
Final Thought
A private equity firm does not buy the company you have built. It buys the company it thinks yours can become without you, then asks you to help build it. That is the last step of the UNLOCK Method: keep scaling beyond the founder. The work that earns a better price is the same work the firm will ask for after closing: a team that sells without you, a plan with numbers in it, and earnings you can prove. Mark has had three exits, one of them a nine-figure private equity rollup. If a sale is a few years away, that work is what his exit planning is for.
Ready to build a revenue engine that runs without you?
Mark works alongside founders as a player-coach — not a slide deck.
Book a 30-minute call