Startup Board of Directors: When You Need One, Who Should Sit on It and How to Run It
Your first outside investor has sent the term sheet, and one line asks for a seat on the board. So you go looking for the board. You find it on a form filed the week the company was set up: your name, and the name of the lawyer who did the filing. Nobody has met. Nobody has voted on anything in years. The request is reasonable, but it raises questions you have never had to answer. Who else should sit there? How often should it meet? And what does a working startup board of directors change?
What Does a Startup Board of Directors Do?
A startup board of directors is the small group that holds legal authority over the company on behalf of its shareholders. In Delaware, where most venture-backed US companies are incorporated, section 141 of the state's corporation law puts it plainly: "The business and affairs of every corporation organized under this chapter shall be managed by or under the direction of a board of directors." Other states use similar wording.
In practice, the board does five things:
- Hires, reviews and pays the chief executive, and replaces them if it has to.
- Approves the yearly plan and budget.
- Approves the big decisions: raising money, borrowing, issuing shares or options, buying or selling a business.
- Watches the numbers and the risks, and asks the hard questions about both.
- Carries legal duties to the company and its shareholders, chiefly a duty of care and a duty of loyalty.
What it does not do is run the business. The chief executive and the team run it day to day. The board directs, checks, and decides the few things that are its to decide. A board that starts managing is as much of a problem as one that never meets.
Do You Need a Formal Board Yet?
If your company is a corporation, it already has a board, even if the board is only you. The real question is whether you need a working one: people other than you who meet, read the numbers and vote. Three questions decide it.
- Do outside investors own part of the company? Anyone who has put serious money in will want a view of how it is used. Investors who lead a round usually ask for a seat as a condition of investing, which is one of the trade-offs of raising venture capital instead of bootstrapping.
- Is a lender, buyer or major customer asking about governance? A bank lending against the business, a large customer checking its suppliers, or a buyer making early enquiries may ask who oversees the chief executive. "Nobody" is an answer that costs you.
- Is a sale or succession about three years away? Buyers pay more for a company that does not depend on its founder, and a board with an independent director, clean minutes and a steady rhythm is evidence of that. A board formed three years out has a track record by the time a buyer looks. It is often the first practical step in planning the exit.
If none of the three is true, a formal board adds cost and process for little return. An advisory board, or one trusted advisor, gives you the outside view without the legal weight. If one is true, start a small working board. If two or three are true, start it this quarter.
Board of Directors vs Advisory Board vs No Board
The difference comes down to votes and duties. A board of directors decides. An advisory board advises, and the owner is free to ignore it.
| Board of directors | Advisory board | No working board | |
|---|---|---|---|
| Who decides | The board, by vote | The owner; advisors have no vote | The owner alone |
| Legal duties | Care and loyalty to the company and its shareholders | None beyond a written agreement | The owner's own |
| Can replace the chief executive | Yes | No | No |
| Cost and effort | Director pay, directors' insurance, four meetings and a pack | Advisor rewards and a few meetings | None |
| Best for | Outside investors, a sale ahead, a hired chief executive | An owner who wants expertise and keeps control | An early company with one owner and no outside money |
Many owner-led companies run both: a small board for the decisions that need a vote, and an advisory board built around specific decisions for expertise the board lacks. The mistake is to call an advisory board a board, or to treat directors as advisors whose views can be set aside.
How Many Board Members Does a Startup Need?
Legally, very few. Delaware's law says the board "shall consist of 1 or more members, each of whom shall be a natural person." A founder alone is a valid board.
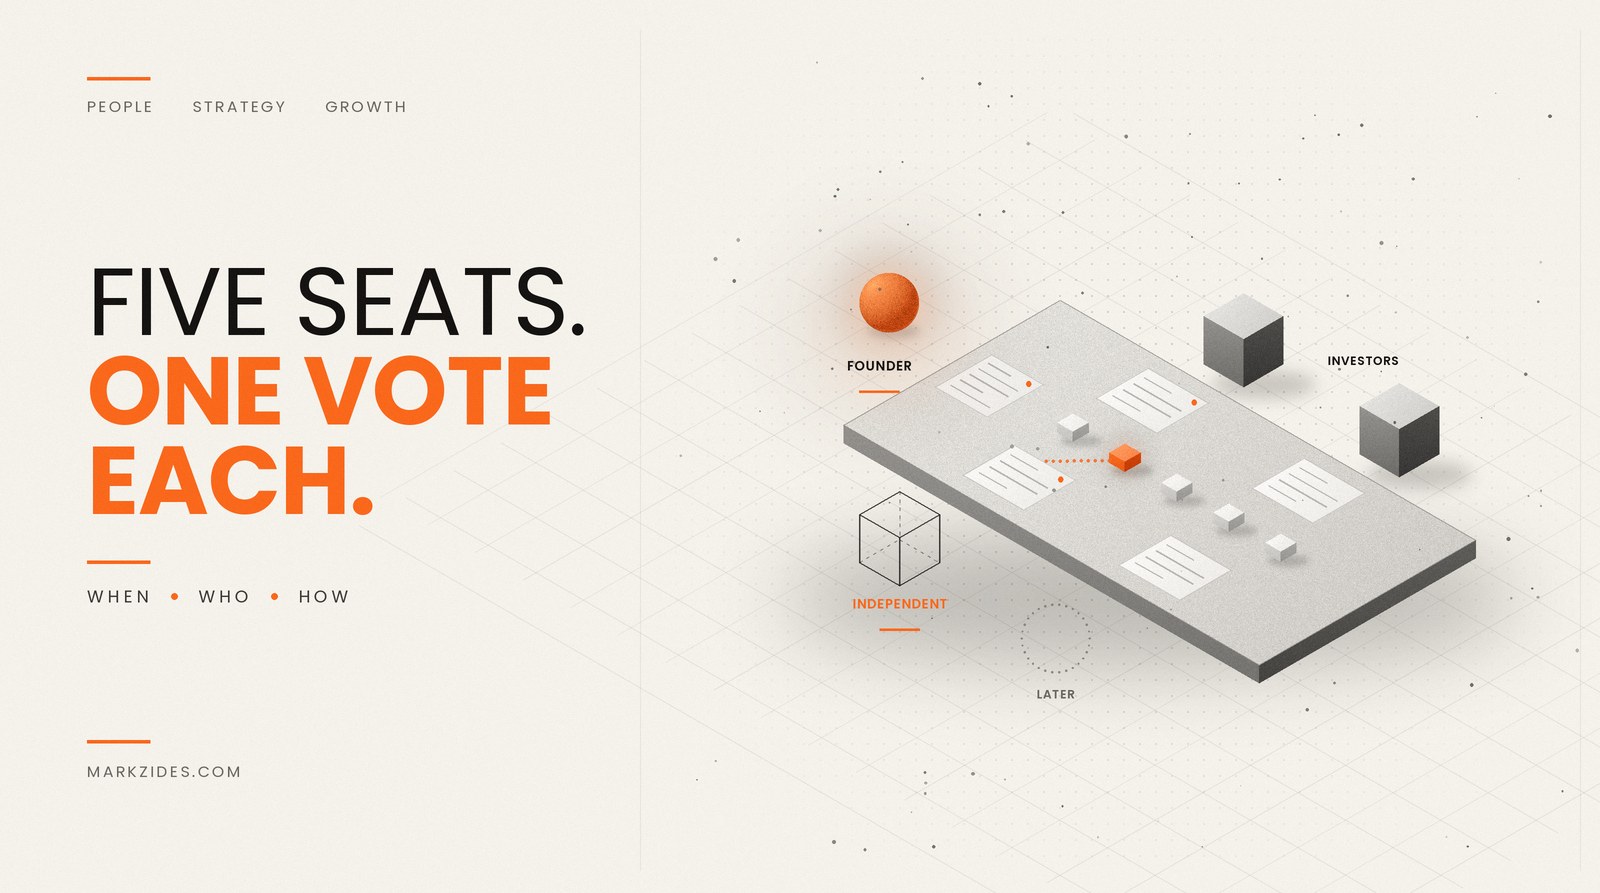
In practice, three is the right size for a first working board, and five suits most companies of $5M to $50M with outside investors or a sale ahead. Keep the number odd so a split vote settles. Above five, meetings slow down, preparation gets thinner, and the real decisions start to happen in side conversations before the meeting.
Size follows the stage, not the ambition. A $3M company with seven directors spends more time managing its board than the board spends helping the company. When a new investor asks for a seat and you already have three, the usual answer is to add a second independent director at the same time. That keeps the number odd and the balance where it was.
Who Should Sit on a Startup Board of Directors
Think in seats, not names. Each seat needs a reason to exist.
- The founder or chief executive. Always on the board. The founder's place on it shifts as the founder grows into the chief executive's job, and shifts again if they later hand that job to someone else and stay on as chair.
- Investor seats. The investor who leads a round usually asks for a seat; smaller investors usually do not get one. An investor director is there to protect their money. That is legitimate, but it is not the same as being independent.
- The independent director. Someone with no stake beyond the seat: not an employee, not an investor, not a friend. They are the person who can tell the founder no, and the person both founders and investors trust when the two disagree.
- Co-owners and family. In an owner-led company, a co-owner may sit by right. A spouse or relative usually should not, unless they own part of the company and understand the duties that come with the seat.
Whatever the seat, look for the same four things. The person has seen a company of the size you are heading for. They can read a set of accounts without help. They will prepare for every meeting. And they will disagree with you in the room rather than after it.
How to Set Up a Startup Board of Directors in 6 Steps
1. Write Down What the Board Decides
List the decisions that need a board vote and the ones the chief executive keeps. The board usually takes the yearly plan and budget, raising money or borrowing above a set amount, issuing shares or options, buying or selling a business, and the chief executive's pay and role. The chief executive keeps everything else, including hires below the leadership team and spending inside the budget. If investors have rights from a funding round, those may add to the board's list.
Do this: Put the list on one page and agree it before the first meeting.
2. Pick the Size
Three seats for a first working board; five once investors hold seats or a sale is near. Odd numbers only.
Do this: Name each seat and the reason for it before you name anyone to fill it.
3. Find the Independent Director
This is the seat that changes a board most, and it is worth taking time over. The section on the first independent director below sets out when to add one and what to look for.
Do this: Write down the gap the independent must fill: your industry, finance, selling a company, or building a sales team.
4. Do the Paperwork
Directors are elected by the shareholders, or appointed as the company's bylaws allow, usually by a short written consent. Check the bylaws or operating agreement for the number of seats and how they are filled, and update them if needed. Buy directors' and officers' insurance before an outside director joins; most will not join without it. A company lawyer should handle this step. It is short work for them, and the rules vary by state.
Do this: Ask your lawyer for the consents, any bylaw changes and an insurance quote in one request.
5. Set the Calendar
Fix four dates for the year, about a quarter apart, before the first meeting. Place each one a few weeks after the quarter closes, so the numbers are final, and after the leadership team's own quarterly planning, so the board reviews a plan rather than writing one. Board meetings belong inside the company's operating rhythm, not beside it.
Do this: Send all four dates as calendar invitations on the day the board is formed.
6. Hold the First Meeting
Use it to approve three things: the decision list, the year's plan and the dashboard the board will see every quarter. Agree how directors will hear about urgent matters between meetings, and how they will approve anything that cannot wait.
Do this: Keep the first agenda to those items, and end with a short session for directors only.
How to Run Board Meetings
Four meetings a year is enough for most companies of this size, with a one-page written update to directors in each month between. Each meeting runs two to three hours. Meet in person where you can; directors disagree more honestly across a table than on a screen.
The board pack. Send it five days before the meeting, so directors arrive with questions instead of reading in the room. Keep the core short:
- A one-page dashboard: revenue, gross margin, cash and runway, pipeline, headcount and three or four numbers specific to the business, each against plan.
- A one-page letter from the chief executive: what went well, what did not, and what worries them.
- The decisions needed, each with a recommendation.
- Supporting detail as appendices, to be read beforehand, not presented.
A standing agenda. Ten minutes for last meeting's minutes and routine approvals. Thirty for questions on the pack, not a presentation of it. About seventy-five for one or two strategic topics. Twenty for decisions. Fifteen at the end for directors without management, which gives the independent director room to raise what they would not say in front of the team.
Minutes a buyer could read. Record each decision, how the vote went and the reasoning in a few lines. Minutes are not a transcript. When a private equity buyer runs its checks, board minutes are among the documents it asks for, and clean ones show a company that was governed, not just owned.
The First Independent Director
Add one when the board gains its first outside seat, when nobody inside the company can tell the founder no, or when a sale is a year or two away. An independent or non-executive director carries the same legal duties as every other director, so choose for challenge and independence, not friendship.
Look for someone who has already done what you are about to do: grown a company through the next stage, or sold one in your industry. Ask your lawyer, your accountant, your investors and other founders for names, and meet several. Ask each how they handled a disagreement with a chief executive; the answer tells you more than the résumé does.
Pay at a private company is usually a small grant of equity that vests over a few years, sometimes with a fee for each meeting. It should be enough for the director to take the seat seriously, and not so much that they depend on it.
Five Board Mistakes Founders Make
- A board on paper only. Consents signed in bulk once a year look fine until an investor or buyer asks to see how the company was governed.
- Seats for friends. A friend on the board rarely says no, which is the one thing the seat is for.
- Too many seats, or an even number. Seven directors at $3M of revenue, or four directors split two and two, both stall decisions.
- Giving away control one seat at a time. Each round's lead investor takes a seat, and two rounds later the founders are outvoted without anyone deciding that they should be.
- Meetings that are status reports. A long slide deck read aloud leaves no time for the decisions the board exists to make.
Frequently Asked Questions
Does a startup need a board of directors?
A corporation must have one, even if the board is only the founder. A working board with outside directors becomes worth its cost when outside investors own part of the company, a lender or buyer asks about governance, or a sale or succession is about three years away.
How many board members should a startup have?
Three for a first working board, and five for most companies with outside investors or a sale ahead. Keep the number odd so votes settle, and add seats in step with the company, not ahead of it. Above five, meetings slow and preparation thins.
What is the difference between a board of directors and an advisory board?
A board of directors has legal authority: it votes, can replace the chief executive and owes duties to the company and its shareholders. An advisory board gives advice the owner is free to ignore. Its members have no vote and no legal duties beyond what they agree in writing.
Who should be on a small company's board of directors?
The founder or chief executive, a seat for any major investor or co-owner, and at least one independent director who has seen a company of the size you are heading for. Friends and relatives rarely belong there unless they own part of the company.
Does an LLC need a board of directors?
Usually not. An LLC is run by its members, or by managers named in its operating agreement, and that agreement can create a board if the owners want one. Many LLCs with outside investors do. The rules vary by state, so check with your lawyer.
Final Thought
A board is not a box to tick when an investor asks for a seat. It is the group that holds the chief executive to account, and in time it is what lets the company raise money, hire leaders and sell without depending on one person. Start with three seats, add an independent director first, and run it on four meetings a year with a pack worth reading. That is the K in Mark's UNLOCK Method: keep scaling beyond the founder. Mark is a six-time founder with three exits, and building the board a growing company needs is part of the work of a growth advisor.
Ready to build a revenue engine that runs without you?
Mark works alongside founders as a player-coach — not a slide deck.
Book a 30-minute call